10 Things to Do With Your Money Before the End of Every Month
The end of the month is a great time to check your finances and prepare for the month ahead.
You don't need a complicated financial system. A simple monthly money routine can help you understand where your money went, identify unnecessary expenses, stay on top of bills, and make steady progress toward your financial goals.
Here are 10 things to do with your money before the end of every month.
1. Review Your Monthly Budget
Start by comparing your planned budget with what actually happened during the month.
Look at your major spending categories, such as:
- Housing
- Food
- Transportation
- Utilities
- Entertainment
- Debt payments
- Savings
Ask yourself:
Did I stay within my budget?
If you overspent in one category, don't simply ignore it. Identify what caused the overspending and decide what you can change next month.
Your budget should evolve as your financial situation changes.
2. Check Where Your Money Went
Review your bank statements, receipts, mobile payments, and other transactions.
Look for expenses you may have forgotten about.
Small purchases can add up quickly, so pay attention to things like snacks, delivery fees, subscriptions, online purchases, and impulse spending.
Once you understand where your money is going, it becomes easier to make better decisions.
3. Pay Any Outstanding Bills
Check whether you have bills that need to be paid before the month ends or shortly after the next month begins.
These might include:
- Rent
- Electricity
- Internet
- Phone bills
- Insurance
- Loan payments
- Credit card payments
- Other recurring expenses
Late payments can sometimes result in additional charges or other consequences.
Creating reminders or using automatic payments where appropriate can make managing bills easier.
4. Transfer Money to Your Savings
Don't wait to see whether you have money left after spending.
If your budget allows, intentionally transfer money toward your savings goals.
This could include:
- Emergency savings
- A home deposit
- Education
- Business savings
- Travel
- Retirement
- Other long-term goals
Even if you cannot save a large amount, consistent contributions can help you build the habit.
Saving regularly matters more than waiting for the perfect month.
5. Review Your Emergency Fund
Your emergency fund is designed to help cover unexpected essential expenses.
At the end of each month, check its balance.
If you had to use some of your emergency savings during the month, create a plan to rebuild it.
If you haven't started an emergency fund yet, consider making it one of your financial priorities.
Start with an amount you can realistically afford and gradually build from there.
6. Check Your Debt Progress
If you're paying off debt, review how much progress you made during the month.
Write down:
- Your current balances
- Payments you made
- Interest or fees charged
- Your next payment dates
If your budget allows, consider whether additional payments toward expensive debt make sense for your situation.
Tracking your progress can help you stay motivated, especially when you're working toward a long-term debt payoff goal.
7. Review Your Subscriptions
Recurring subscriptions are easy to forget.
Review payments for:
- Streaming services
- Mobile apps
- Software
- Memberships
- Online services
- Other recurring charges
Ask yourself:
Did I actually use this service this month?
If the answer is no, consider canceling or pausing it.
Removing even a few unnecessary recurring expenses can free up money for savings or other financial priorities.
8. Check Your Progress Toward Financial Goals
Review the goals you set for yourself.
Maybe you're working toward:
- Building an emergency fund
- Becoming debt-free
- Saving for a home
- Starting a business
- Investing for the future
- Building retirement savings
Compare where you are now with where you wanted to be.
If you're behind, don't automatically abandon your goal. You may simply need to adjust your timeline, contribution amount, or spending plan.
9. Plan Next Month's Budget
Don't wait until the new month is already underway.
Estimate your expected income and expenses ahead of time.
Consider upcoming expenses such as:
- Birthdays
- School expenses
- Travel
- Repairs
- Insurance
- Annual subscriptions
- Medical expenses
- Holidays or special events
Planning for irregular expenses can reduce the chances that they become financial surprises.
Give every part of your expected income a purpose before the month begins.
10. Set One Financial Priority for the New Month
Instead of trying to improve everything at once, choose one main money goal for the next month.
For example:
“I will save an additional ₦20,000 this month.”
Or:
“I will reduce my eating-out expenses by 30%.”
Or:
“I will make an additional payment toward my debt.”
A clear, measurable goal can make it easier to stay focused.
Your End-of-Month Money Checklist
Before the month ends, make sure you've:
- Reviewed your budget
- Checked your spending
- Paid outstanding bills
- Added money to savings
- Reviewed your emergency fund
- Checked your debt progress
- Reviewed subscriptions
- Measured your financial goals
- Planned next month's budget
- Chosen your next financial priority
You can complete this routine once every month and keep a record of your progress.
Why a Monthly Money Review Matters
Your financial situation won't always go exactly according to plan.
Unexpected expenses happen. Income can change. Priorities can shift.
A monthly review gives you an opportunity to catch problems early and adjust your plan.
Instead of wondering where your money went several months later, you'll know what happened and what you need to do next.
Over time, this routine can help you become more intentional with your spending, saving, and financial decisions.
Final Thoughts
Managing your money isn't something you do once and forget about.
It's an ongoing process.
Before the end of every month, take some time to review your budget, expenses, savings, debt, bills, and financial goals.
Then prepare your plan for the next month.
You don't have to make dramatic changes overnight. Small financial improvements repeated month after month can create meaningful progress over time.
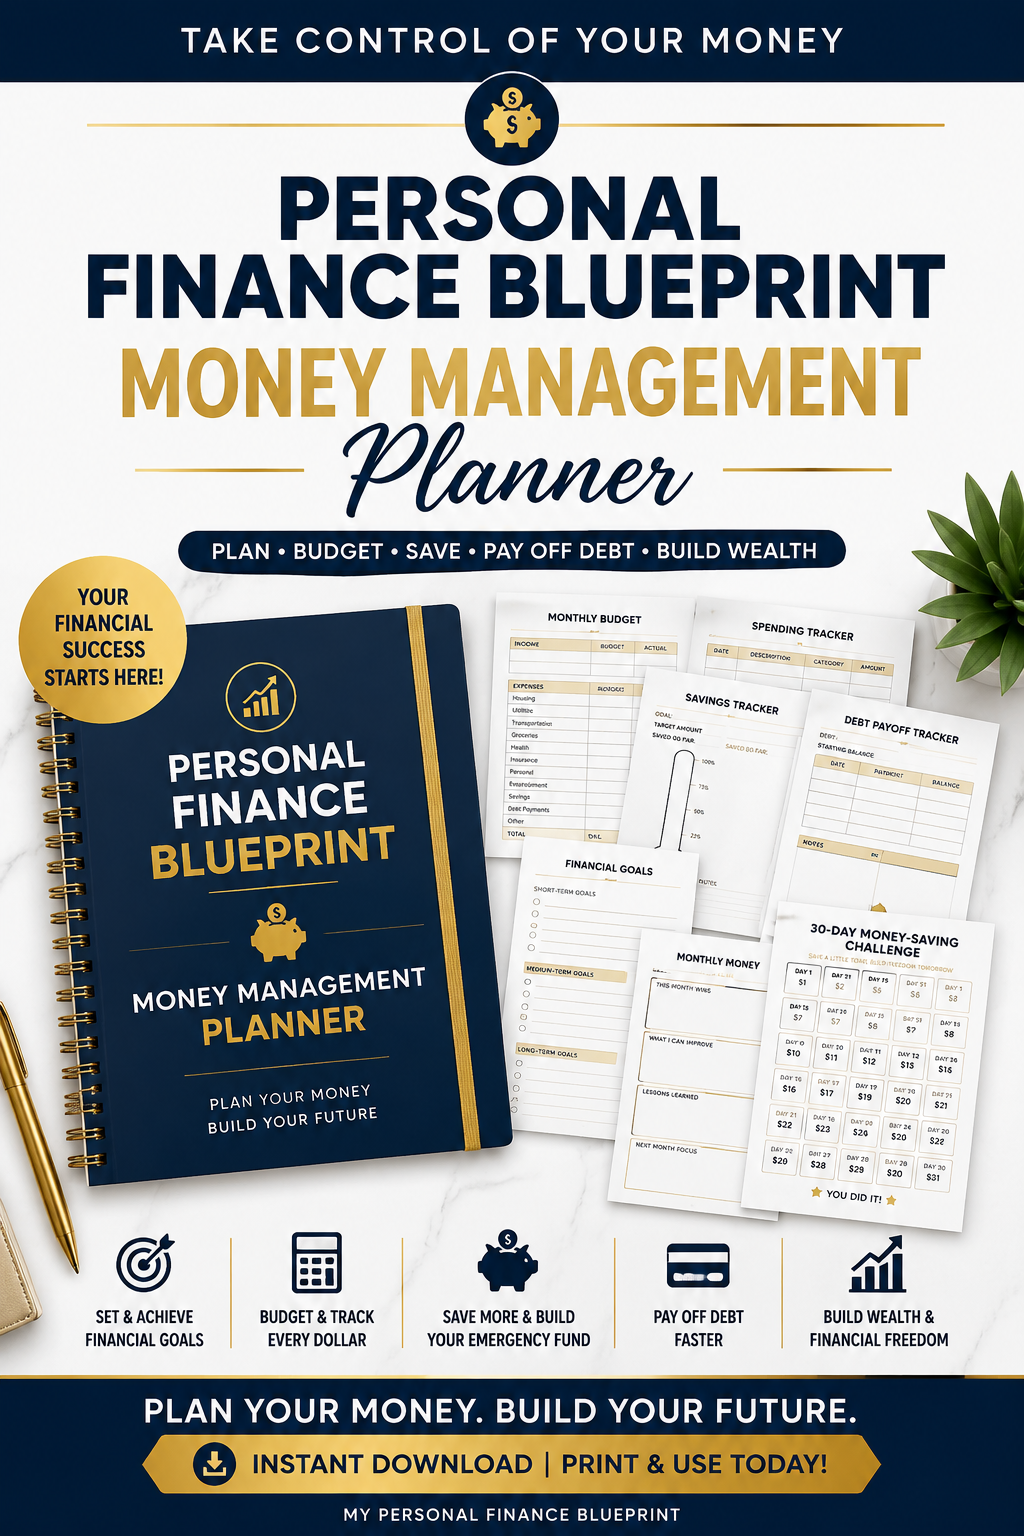
If you want a structured way to track your budget, spending, savings, debt, and financial goals, the Personal Finance Blueprint – Money Management Planner can help you organize your monthly finances in one place.
https://myblueprinthub.com/products/personal-finance-blueprint-money-management-planner?variant=53371043152161
Digital Products
Disclaimer: This article is for educational purposes only and is not personalized financial advice. Financial decisions should be based on your individual income, expenses, goals, and circumstances.


Comments
Post a Comment